Roof Insurance Claim Help for Storm Damage in Lapeer County
Your claim belongs to you, and the decisions are between you and your insurer. What we bring is a clear record of the damage and a written repair estimate, so the conversation starts from facts.
- Licensed & InsuredResidential and commercial
- 25+ Years of ExperienceOn Lapeer County roofs
- Free InspectionsWritten estimates
- Licensed & Insured
- 25+ Years of Experience
- Residential & Commercial Roofing
- Free Inspections & Written Estimates
- Serving Lapeer County, Michigan
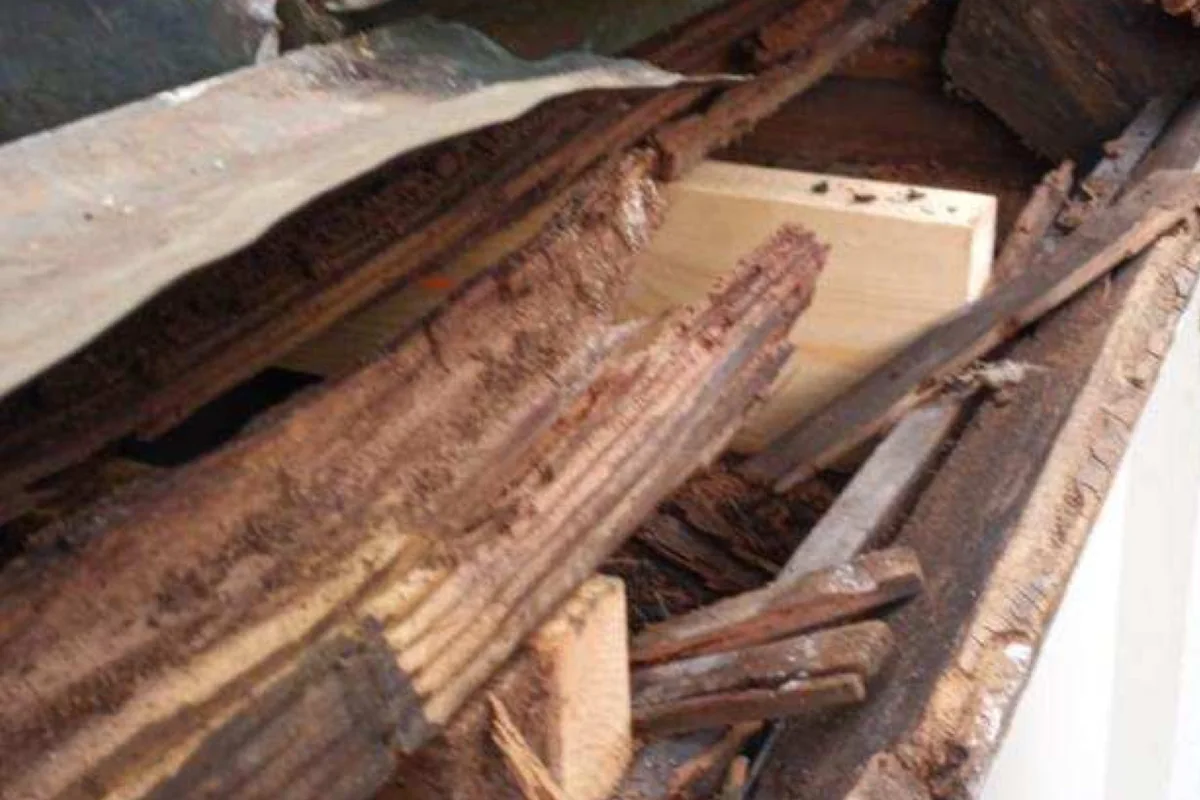
What should you do first after storm damage?
Start with safety: stay off the roof, keep clear of downed lines, and move people and valuables away from leaks. Then photograph the damage from the ground and inside the house, and take reasonable steps to stop more water from getting in, such as a tarp. Keep every receipt for that protection work.
Homeowner policies commonly ask you to prevent further damage once you know about it. That does not mean climbing a ladder in the rain. It means arranging emergency roof tarping or temporary sealing, catching drips, and drying out what you can. Your insurer may ask what was done and what it cost, so save invoices and take before-and-after pictures.
Write down the date and time of the storm, too. If neighbors had damage from the same storm, note that. These details help when you call your insurer to report the loss.
How do we document roof damage?
We inspect the whole roof, not just the obvious spot. We photograph damaged shingles, hail hits, lifted tabs, broken ridge caps, flashing, gutters and vents, plus any water stains in the attic. Then we write a repair estimate that lists what we found and what it would take to fix it properly.
Good documentation separates storm damage from ordinary wear. Hail leaves bruises and granule loss in a random pattern across a slope; wind creases tabs and lifts shingles along edges and ridges. Old cracking, curling or long-term flashing failure looks different, and we will tell you honestly which is which. A roof can have both, and an adjuster will look for the difference too.
What you receive from us:
- Photos of the damage, organized by area of the roof
- A written estimate describing the repair
- Notes on anything we saw that looks like age or wear rather than storm damage
If hail is the main concern, our hail damage repair page explains what we look for. For wind, debris and mixed damage, see storm damage repair. If the problem is a leak with an unclear source, a roof leak inspection traces it first.
What happens during an adjuster's inspection?
After you report the claim, your insurer typically sends an adjuster to look at the roof and any interior damage. They inspect, measure, take their own photos and later send you their findings. If you want us there, we can meet the adjuster on site and point out the damage we documented.
Having the roofer who inspected the roof present can help make sure nothing is missed, such as damage on a back slope or soft decking. It is your choice. Some homeowners prefer to handle the visit alone and share our photos and estimate afterward, and that works too.
When the insurer's findings arrive, read them carefully and compare them with our estimate. If something does not match, ask your insurer about it directly. Questions about coverage, depreciation or what the policy pays for are between you and your insurance company.
What can we do, and what can't we do?
We can inspect, photograph and document storm damage, give you a written repair estimate, and meet your adjuster if you ask. We cannot file the claim for you, negotiate with your insurer, or interpret your policy. We are not public adjusters, and no roofer can promise a claim will be approved.
You own the claim from start to finish. You report it, you talk with your insurer, and you make the decisions. Before you file, check your policy or call your agent about:
- Whether wind and hail damage are covered, and how
- Your deductible, which may be a set amount or a percentage for wind and hail
- How long you have to report damage and finish the claim
- What records they want for emergency protection costs
Every policy is different, so the answers for your home come from your insurer, not from us.
Will we waive or pay your deductible?
No. We never offer to waive, absorb, cover or rebate your insurance deductible, and you should be wary of any contractor who does. Your deductible is your share of the loss under your policy. A contractor waiving it puts your claim at risk, and in Michigan it is against the law.
Our estimates reflect the real cost of the repair. What your insurer pays, and what you pay, follows from your policy. If your insurer approves replacing the roof, we can do the full roof replacement for you.
Help in your part of the county
Wind runs hard across the open farmland around Imlay City, limbs come down on wooded lots in Dryden, and lake homes in Otter Lake catch wind straight off the water. Wherever you are in Lapeer County, the documentation process is the same.
Reporting storm damage soon? We can document the roof and give you a written estimate to share with your insurer.
Why choose Lapeer County Roofing
Licensed and insured
Lapeer County Roofing is licensed and insured for residential and commercial roofing work across Lapeer County.
25+ years of experience
Our crew brings 25+ years of experience to every repair, replacement and inspection on homes and commercial buildings.
Free inspection with photos
We inspect the whole roof, photograph what we find and show you the damage before we recommend anything.
A written estimate
You get the price in writing before work starts, with no cost and no obligation for the inspection.
Adjuster meetings on request
For storm claims we document the damage and can meet your insurance adjuster on site if you ask us to.
Cleanup when we finish
We pick up nails, old shingles and debris before we leave, so your yard and driveway are clear.
Frequently asked questions
Should I call my insurer or a roofer first?
If water is coming in, protect the house first and arrange a tarp or seal, keeping receipts. Then report the damage to your insurer as your policy requires. Many homeowners also get a roofer's inspection early so they understand the damage before the adjuster visits. Check your policy for reporting deadlines either way.
Can you tell me if my claim will be approved?
No, and no honest roofer can. Approval and payment are decided by your insurer under the terms of your policy. What we can tell you is what damage we found, whether it looks like storm damage or age, and what the repair involves. That information helps, but the decision belongs to the insurance company.
Do I have to use the roofer my insurance company suggests?
Policies and insurers differ, so ask yours directly. In many cases homeowners can choose who repairs their home. If you would like us to do the work, we can provide our photos and written estimate for you to share with your insurer, and we will answer any questions you have about our repair plan.
What if the adjuster finds less damage than you did?
Compare their report with our photos and estimate line by line. If something is missing, contact your insurer and ask how to request a review; many policies explain that process. We can share our documentation with you again or clarify what we saw, but you handle the conversation with your insurer, because we do not negotiate claims.
Is there a charge for documenting damage for a claim?
No. The roof inspection, photos and written estimate are free, whether or not you end up filing a claim. If the damage turns out to be wear rather than storm damage, we will say so, and you can decide whether a repair makes sense for you without a claim involved.
Storm damage on your roof?
Ask for a free inspection and estimate anywhere in Lapeer County.